When a shipment is lost or damaged, many shippers expect the carrier to pay for it. The carrier usually does owe something. But that amount is set by law, capped well below the value of most commercial cargo, and can drop to zero under a long list of defenses. Marine cargo insurance works on a completely different basis. Understanding the gap between the two is the difference between recovering what your cargo was worth and recovering a fraction of it.
What Carrier Liability Really Means
Carrier liability is the carrier’s legal responsibility for cargo in its care, and international conventions and statutes define how far it goes. It isn’t insurance. It’s a limited obligation the carrier carries, and the rules are written to cap the carrier’s exposure, not to make you whole.
Ocean Freight: $500 Per Package
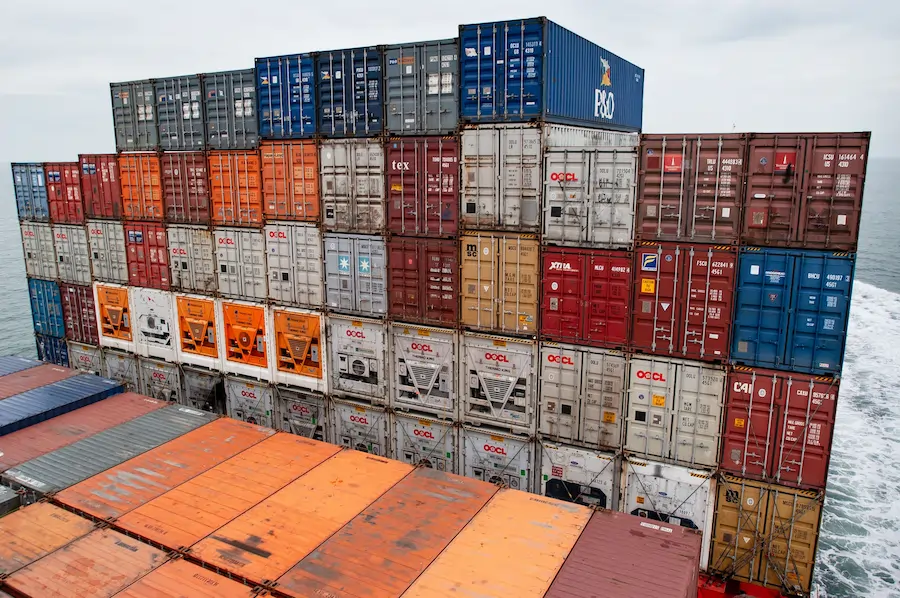
For ocean shipments to or from the United States, carrier liability is governed by the Carriage of Goods by Sea Act, known as COGSA. Under COGSA, an ocean carrier can limit its liability to $500 per package, or per customary freight unit for goods not shipped in packages. What counts as a package depends largely on how the cargo is described on the bill of lading. If a full container of goods is listed as a single package, the recovery for a total loss could be $500, whether the contents were worth $5,000 or $500,000.
COGSA also gives carriers a set of statutory defenses. If a loss results from perils of the sea, fire, or certain navigational errors, for example, the carrier may owe nothing at all. Even when you do have a valid claim, recovery depends on filing correctly and on time. COGSA claims are generally subject to a one-year time limit for bringing suit.
Air Freight: Limited by Weight
For international air shipments, carrier liability falls under the Montreal Convention, which limits recovery by weight rather than value. As of December 28, 2024, the limit is 26 Special Drawing Rights per kilogram, roughly $35 per kilogram depending on exchange rates. That can leave high-value, lightweight shipments badly underprotected. A 100-kilogram shipment of electronics worth $50,000 would be limited to roughly $3,500 in carrier liability. Air carriers can also avoid liability in certain situations, such as damage caused by the nature of the goods themselves or by packing they didn’t perform.
Domestic Moves Have Limits Too
The inland legs of a shipment carry their own terms. Domestic truck carriers commonly limit their liability through their tariffs and bills of lading. Cargo moving on a single door-to-door journey can pass through several liability regimes, each with its own cap, and many shippers never look at any of them until something goes wrong.
What Marine Cargo Insurance Does Differently
Marine cargo insurance protects the cargo owner, not the carrier. Instead of asking whether the carrier is legally at fault, a cargo policy asks whether the loss is covered under the policy. With broad all-risk coverage, written under Institute Cargo Clauses (A), you’re covered for physical loss or damage from any cause not specifically excluded, without having to prove the carrier did anything wrong. Narrower named-peril coverage, such as Institute Cargo Clauses (C), costs less but covers only the risks listed in the policy.
Policies are typically written at the cargo’s CIF value plus 10%, so coverage reflects what the goods are actually worth, including freight and related costs. Cargo insurance can also follow the shipment across ocean, air, and inland legs, closing the gaps that different carrier liability regimes leave behind.
The Risk Most Shippers Don’t Know About: General Average
General average is a long-standing maritime principle. When a vessel’s crew makes an intentional sacrifice or incurs extraordinary expense to save the voyage, such as jettisoning cargo or fighting a fire, every cargo owner on board shares the cost in proportion to the value of their goods. That applies even if your cargo arrives undamaged. The carrier’s liability doesn’t help here, because general average is a cost shared by cargo owners, not a claim against the carrier. Cargo can be held at destination until each owner provides security for its share. A cargo insurance policy typically covers the general average contribution and provides the guarantee needed to release your goods. Without insurance, that security comes out of your own pocket.
What Cargo Insurance Won’t Cover
Cargo insurance has limits too. Standard exclusions include losses caused by inadequate packing, the inherent nature of the goods, and delay. War and strikes are usually excluded from a base policy but can be added. Packaging deserves particular attention: a claim can be denied if the goods weren’t packed to withstand normal transit, so documenting your packing standards is worth the effort.
Who Should Arrange the Coverage
Whether you or your trading partner is responsible for insuring a shipment depends on the terms of sale. Your Incoterms define the point where risk transfers from seller to buyer, and that tells you who needs coverage for each leg. If you’re buying on terms where the seller arranges insurance, confirm the coverage level, since sellers often buy the minimum required.
Protecting What Your Cargo Is Worth
Carrier liability is a legal floor, not a safety net. For regular importers and exporters, the real question isn’t whether the carrier is liable. It’s whether you’d recover the value of your goods if something went wrong. Marine cargo insurance is how most commercial shippers close that gap.
Jade International has helped importers and exporters move freight for nearly four decades. If you’d like to talk through how your shipments are protected, reach out to our team.